FBR Filer vs Non-Filer Tax Rates 2026–27: Viral Chart Fact-Checked
A widely shared comparison chart mixes correct figures with stale or over-broad labels. FPN checks the high-interest rows against FBR’s Tax Year 2027 rate card and explains what each percentage actually applies to.
Swipe or scroll through all 3 original FPN explainers. The searchable tables below remain the authoritative page content.
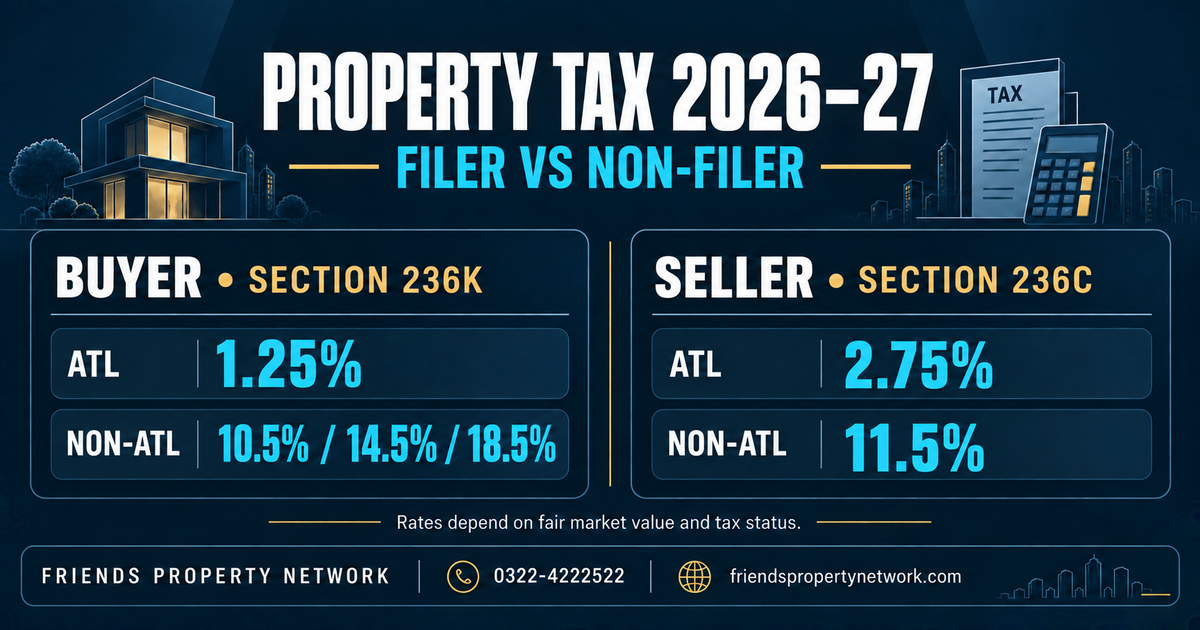
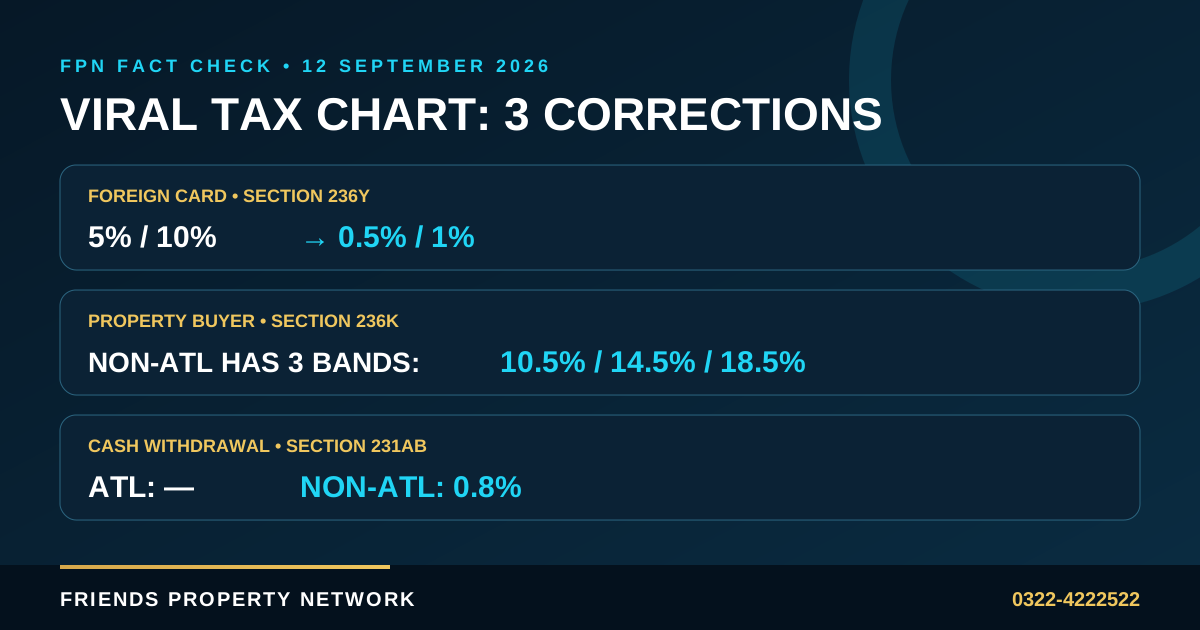
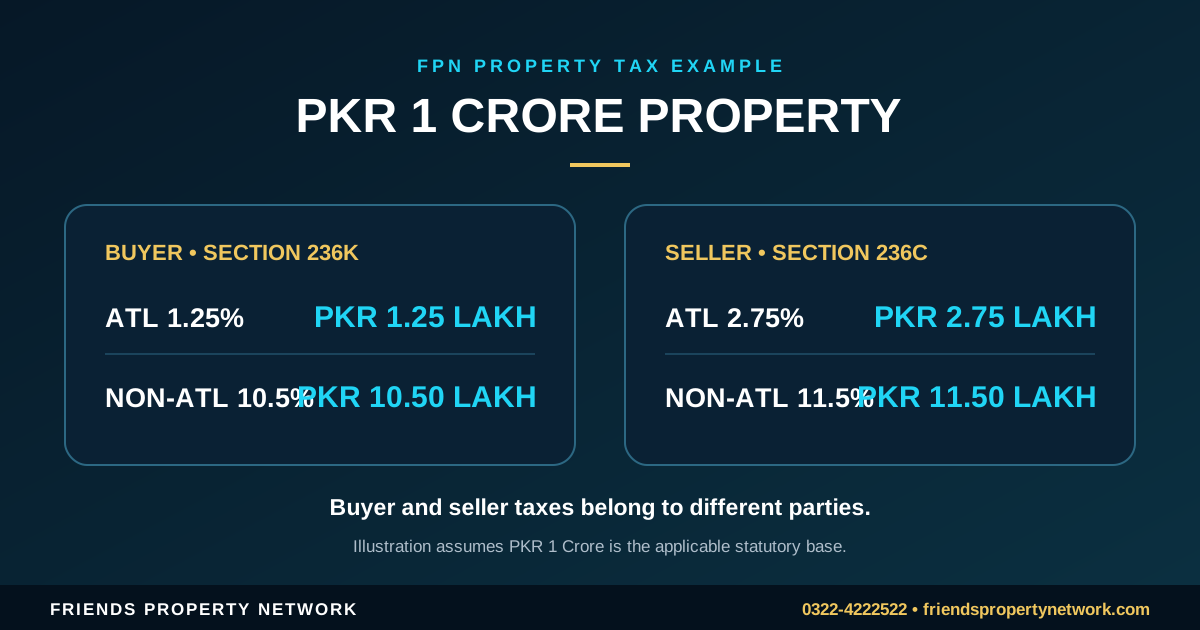
01Original FPN tax explainer • based on the official Tax Year 2027 rate card checked 12 September 202602Original FPN fact-check graphic • simplified social charts need category and threshold context03Original FPN calculation • buyer and seller amounts belong to different parties
Verified figures
What the current FBR rate card actually shows
Tax Year 2027 card updated to 30 June 2026. ATL means the person appears on the Active Taxpayers’ List. A dash means the cited section does not impose an ATL rate, not that every banking transaction is tax-free.
Transaction / section
ATL rate
Not on ATL
Important scope
Property purchase • 236K • FMV up to PKR 5 Crore
1.25%
10.5%
Buyer; statutory fair market value
Property purchase • 236K • above PKR 5 to 10 Crore
1.25%
14.5%
Buyer; statutory fair market value
Property purchase • 236K • above PKR 10 Crore
1.25%
18.5%
Buyer; statutory fair market value
Property transfer/sale • 236C • all three published bands
2.75%
11.5%
Seller; gross consideration received
Cash withdrawal • 231AB
—
0.8%
Only a person not on ATL; aggregate daily withdrawals above PKR 50,000 under the Ordinance
Foreign card remittance • 236Y
0.5%
1%
Amount remitted abroad through credit, debit or prepaid card
Bank account/deposit profit • 151
20%
40%
Specific bank/financial-institution account or deposit category
Prize bond or crossword prize • 156
15%
30%
Raffles, lotteries and some other winnings use a different row
Brokerage/commission • 233 • residual category
12%
24%
Advertising and qualifying life-insurance agents have separate rates
Verified figures
PKR 1 Crore property example
Illustration only. It assumes PKR 1 Crore is the applicable Section 236K fair market value and the seller’s gross consideration for 236C. Buyer and seller taxes are not added to one person’s bill.
Party
ATL calculation
Not on ATL
Difference
Buyer • 236K
1 Crore × 1.25% = PKR 1.25 Lakh
1 Crore × 10.5% = PKR 10.50 Lakh
PKR 9.25 Lakh
Seller • 236C
1 Crore × 2.75% = PKR 2.75 Lakh
1 Crore × 11.5% = PKR 11.50 Lakh
PKR 8.75 Lakh
Verified figures
Why the viral chart should not be copied as-is
FPN correction table based on the cited current official documents.
Shared-chart claim
Current position
Publishing decision
Foreign card transaction: 5% vs 10%
FBR card shows 0.5% ATL and 1% non-ATL under 236Y
Corrected by one decimal place
Property buyer: 1.25% vs 10.5%
Non-ATL rate rises to 14.5% and 18.5% in higher FMV bands
All three buyer bands shown
Cash withdrawal: 0% vs 0.8%
231AB applies to a person not on ATL; ATL column is a dash
Not described as a universal 0% ATL tax
Dividend: 15% vs 30%
That pair fits a listed REIT/other category, but several dividend categories differ
No universal dividend headline
Vehicle purchase/registration: 1x vs 3x
FBR lists cc/value bands and separate registration/transfer situations
No vague multiplier presented as a calculation
Surveyor/services: 11% vs 22%
Service and supply rates depend on classification; no universal “surveyor tax” row matched
Omitted pending transaction classification
Tuition/education: 0.5% vs 2.5%
No matching current row was established in the cited 2026–27 rate card
Not republished
Buyer questions
Frequently asked questions.
What is the property purchase tax for an ATL filer in Pakistan in 2026–27?+
FBR’s Tax Year 2027 rate card shows 1.25% under Section 236K for an ATL buyer in each of the three fair-market-value bands.
What are the non-filer property buyer rates?+
For a buyer not on ATL, the published Section 236K rates are 10.5% up to PKR 5 Crore, 14.5% above PKR 5 Crore through PKR 10 Crore and 18.5% above PKR 10 Crore.
What is the seller tax under Section 236C?+
The current rate card shows 2.75% for an ATL seller and 11.5% for a seller not on ATL across all three published gross-consideration bands.
Is cash withdrawal tax 0% for a filer?+
Section 231AB is written for a person not appearing on ATL, so the FBR card shows a dash in the ATL column and 0.8% in the non-ATL column. The Ordinance refers to aggregate withdrawals exceeding PKR 50,000 in a day.
Is the foreign credit-card tax still 5% and 10%?+
Not in the current cited rate card. Section 236Y shows 0.5% for ATL and 1% for non-ATL on amounts remitted abroad through credit, debit or prepaid cards.
Does this table calculate my final tax liability?+
No. These are withholding or advance-tax references. Your transaction facts, exemptions, adjustable treatment and return position need transaction-specific advice and official payment evidence.
01
The shared image is useful as a warning, not as a current rate card
Its property seller figures and several familiar pairs can be matched to the current FBR card, but other rows are stale, incomplete or labelled too broadly. The clearest error is the foreign-card remittance row: the current Section 236Y rates are 0.5% and 1%, not 5% and 10%. The property-purchase row hides two higher non-ATL bands. A visually polished repost would spread those errors faster, so FPN rebuilt the graphic around the verified property rates and moved the category detail into searchable text tables.
02
“Filer” is search language; ATL status controls these comparisons
People commonly ask for filer and non-filer rates, while the FBR card labels the columns ATL and Non-ATL. A previously filed return, tax registration or NTN does not by itself prove that a person appears on the live ATL for the transaction date. Check the buyer and seller separately before bayana or transfer. Keep the verification result with the computation and official PSID/CPR record. This article does not decide whether a particular person qualifies for an exemption or how an adjustable tax will settle in a return.
03
Property buyers must select the correct value band
Section 236K uses the statutory fair-market-value framework, not automatically the dealer’s asking price or the parties’ negotiated figure. Up to PKR 5 Crore the non-ATL rate is 10.5%; it becomes 14.5% above PKR 5 Crore through PKR 10 Crore and 18.5% above PKR 10 Crore. ATL remains 1.25% in the three published bands. Identify the exact city, locality, property type, area and applicable valuation before multiplying a percentage. A wrong base can make an arithmetically correct answer legally wrong.
04
Buyer 236K and seller 236C are separate obligations
Section 236K is collected from the purchaser. Section 236C is collected from the seller or transferor and uses gross consideration received. The current seller rates are 2.75% on ATL and 11.5% when not on ATL across the published consideration bands. Do not combine both sides into a single “transfer tax” and charge it to one party without contractual and legal support. Society transfer fees, NDC dues, Punjab duties, registration expense, professional fees and commission are also separate from these federal percentages.
05
The non-property rows need their full labels
Bank-account profit is shown at 20% versus 40% for the specified Section 151 account/deposit category, while other profit-on-debt categories differ. Prize bonds and crossword prizes use 15% versus 30%, but raffles and lotteries appear separately at 20% versus 40%. Brokerage and commission uses 12% versus 24% only for the residual category; advertising agents and qualifying life-insurance agents have separate rows. Vehicle taxes change by engine capacity, value and whether the event is purchase, registration or transfer. A universal two-column poster cannot safely replace the rate card.
06
Cash withdrawal and card remittance need two precise corrections
Under Section 231AB the current rate is 0.8% for a person whose name is not on ATL, and the Ordinance refers to aggregate cash withdrawals in a day exceeding PKR 50,000. The ATL column is shown as a dash, so “0%” is a misleading label for the section. For amounts remitted abroad through credit, debit or prepaid cards, Section 236Y currently shows 0.5% ATL and 1% non-ATL. This is one-tenth of the 5% and 10% figures printed in the supplied image.
07
Property transaction document checklist
Prepare the tax file alongside the title and transfer file. The percentage is the last step, not the first.
Buyer and seller CNIC/NTN details and transaction-date ATL checks
Exact plot, house, apartment or commercial-unit identity and ownership chain
Applicable FBR fair market value and the separate gross consideration
Written Section 236K and 236C computation showing who pays each amount
Current society or authority transfer charges and fresh NDC/dues statement
Provincial duties, registration and professional costs calculated separately
Official PSID/CPR and traceable payment evidence
Independent tax and legal review where title, valuation or exemption is uncertain
08
FPN publishing and due-diligence note
This article is an independent explanation of official material checked on 12 September 2026. It is not issued by FBR, does not reproduce the FBR logo and is not a tax return opinion or payment demand. Rates, valuations, ATL status and transaction rules can change. Confirm the live position through FBR records, the competent transfer authority and a qualified tax adviser before payment. For a Lahore property tax checklist, send the exact property details to Friends Property Network on WhatsApp 0322-4222522.
Verification note
Published and updated 12 September 2026 after checking FBR’s 18-page Withholding Income Tax Rate Card updated to 30 June 2026 under Finance Act 2026 and the Income Tax Ordinance amended to the same date. The user-supplied chart was treated as a fact-check lead, not an official or current source. This article reproduces only categories and limits that can be matched to the current FBR material. The rate card itself says the statute prevails if there is a contradiction. “Filer” is used in the headline because people search that phrase; the operative rate-card distinction is whether a person appears on the Active Taxpayers’ List (ATL). Information may change after publication; always obtain the latest official document before acting.
Friends Property Network is not responsible for project delays, non-delivery, possession delays, escalation or developer-imposed charges, approval changes, investment loss or developer default. Conduct independent legal, financial and technical due diligence before investing.